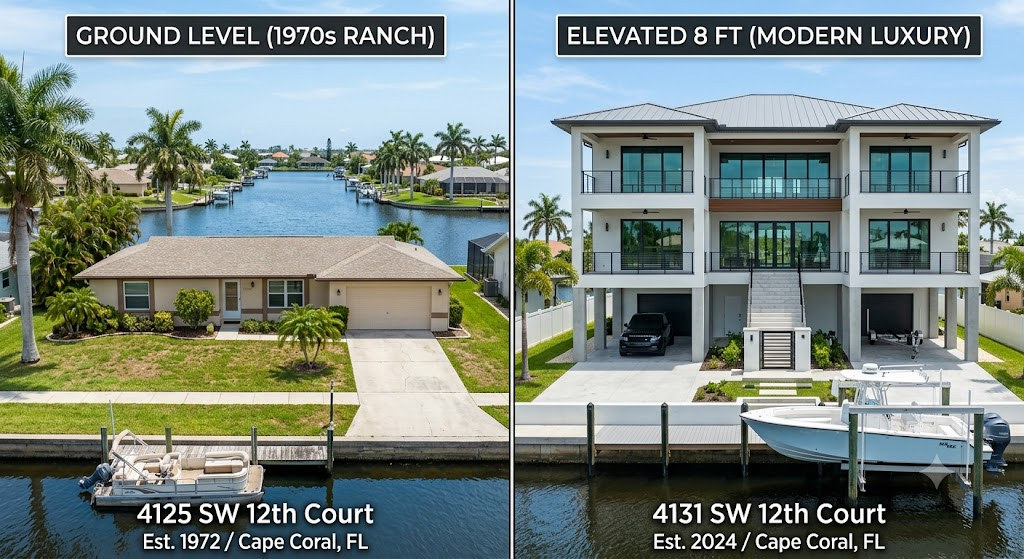
The FEMA 50% Rule is a strict federal floodplain regulation enforced by the City of Cape Coral. It mandates that if the cost to repair, reconstruct, or improve an existing home equals or exceeds 50% of its depreciated market value before the damage occurred, the entire structure must be brought into full compliance with current flood codes. This usually requires elevating the home’s lowest floor above the Base Flood Elevation (BFE) or completely rebuilding the structure. Failure to comply can result in permit denial, severe fines, or the loss of flood insurance.
If you own an older property in Cape Coral and are planning a major renovation, or if you have recently suffered catastrophic Category 3 water damage, there is one regulation that holds total power over your property’s future: The FEMA 50% Rule.
Many homeowners begin with plans for what they believe is a straightforward hurricane restoration or a luxury kitchen remodel, only to be stopped in their tracks by the City of Cape Coral Building Department. Once your project crosses the 50% threshold, your standard repair project transforms into a mandatory structural elevation or a total teardown.
Understanding the mathematics, the legal definitions, and the loopholes of this rule is the difference between a successful remodel and financial ruin.
(Developer Note: Insert a contextual internal link to the Pillar Page here).
Are you navigating the chaotic aftermath of a major flooding event? Refer to our Complete Guide to Flood Damage Restoration in Cape Coral to ensure you don’t make critical compliance errors during the dry-out phase.
1. The Mathematics of the 50% Threshold
The concept of the FEMA 50% Rule applies to what the local government defines as “Substantial Improvement” or “Substantial Damage”.
Whether you are voluntarily adding a new wing to your house (Improvement) or involuntarily fixing a home gutted by a storm surge (Damage), the City of Cape Coral staff will use a strict formula to evaluate your building permit application.
The Calculation:
Total Cost of Improvements or Repairs ÷ Depreciated Market Value of the Building ≥ 50%
If this ratio hits 50% or higher, your existing home is reclassified, and you are legally required to meet the floodplain management regulations designed for brand new construction.
What Counts Towards the “Total Cost”?
The city’s calculation is comprehensive. The term “costs of repair” includes all work necessary to restore the building to its pre-damaged state. This means you cannot simply omit line items to artificially stay under the threshold. The total cost must include:
- All construction materials and structural lumber.
- All labor (even if you are doing the work yourself, must be calculated at current market rates).
- Contractor overhead and profit margins.
What is Excluded from the Calculation?
Fortunately, you can strategically exclude costs that are not directly tied to the primary structure. This includes:
- The market value of the raw land the house sits on (Land value is always excluded from the structure’s market value).
- Outside improvements, such as driveway paving or landscaping.
- Detached accessory structures, swimming pools, and permit fees.
- Plug-in appliances.
2. What Happens if You Cross the 50% Line?
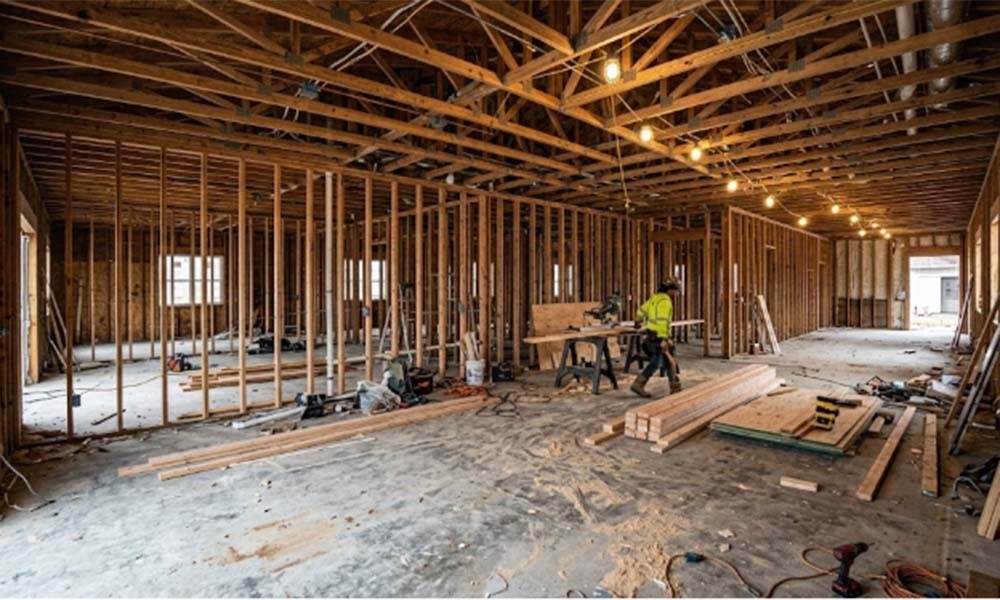
If your project is officially deemed a Substantial Improvement or Substantial Damage, your current property is considered “non-conforming.” You cannot simply replace the drywall and move back in.
To achieve compliance in Cape Coral, you generally have two drastic paths:
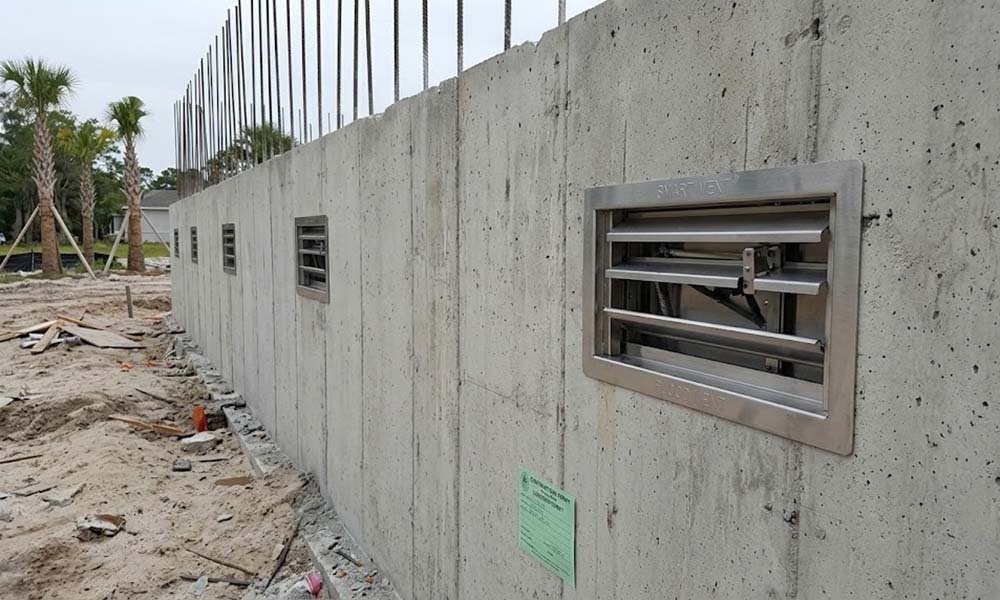
- Elevate the Structure: You must physically raise the building so that its lowest floor sits at or above the Base Flood Elevation (BFE) plus one foot of freeboard at a minimum. In higher-risk coastal zones, this means putting the house on massive concrete pilings or building a compliant stem wall foundation.
- Raze and Rebuild: In many cases, especially with Cape Coral’s older slab-on-grade homes from the 1970s and 1980s, elevating a crumbling block home is architecturally impossible or financially absurd. The only option is to raze (demolish) the entire building and construct a new, fully compliant home elevated safely above the BFE.
3. Why Cape Coral Enforces This Rule So Ruthlessly
You might wonder why the city building department is so inflexible regarding these permits. The answer lies in federal pressure and local insurance economics.
Cape Coral participates in the National Flood Insurance Program (NFIP), which is managed by FEMA. The 50% rule is a strict federal prerequisite for the city to remain in the program. FEMA’s goal is to prevent the American public from continually paying to rebuild vulnerable, low-lying homes that flood repeatedly.
If Cape Coral officials turn a blind eye and allow homeowners to illegally rebuild non-compliant homes in the floodplain, FEMA can impose severe penalties. Recently, FEMA has cracked down hard on local Florida municipalities, threatening to downgrade discounts or kick entire counties out of the federal flood insurance program altogether.
With the introduction of FEMA’s Risk Rating 2.0 system, flood insurance premiums in Lee County are already skyrocketing, with some average annual premiums projected to triple. If the city loses its NFIP standing, homes in Cape Coral would become practically uninsurable, crashing the local real estate market. Therefore, the city has zero tolerance for unpermitted work or fraudulent cost reporting.
4. The Private Appraisal Strategy: Protecting Your Margins
The most critical variable in the FEMA 50% equation is the Depreciated Market Value of your home before the damage occurred.
By default, the city may look at the Lee County Property Appraiser’s assessed value. However, tax-assessed values are notoriously much lower than actual market values. If you use a low tax-assessed value as your baseline, your 50% budget will be tiny, and even a modest kitchen remodel will trigger the requirement to elevate your home.
The Solution: You have the legal right to hire an independent, licensed professional appraiser to determine the true, depreciated market value of the building. City of Cape Coral staff will review this private appraisal. A private appraisal almost always values the structure significantly higher than the county tax rolls.
If your home’s structure is appraised at $400,000 instead of the county’s $250,000, your allowable repair budget just jumped from $125,000 to $200,000, often saving the home from a forced demolition.
5. The AMO Excellence Advantage: Navigating the Red Tape
Navigating the FEMA 50% Rule requires a delicate balance of aggressive moisture mitigation, exact insurance estimating, and strategic architectural planning. If you hire a standard water damage franchise to gut your home, they will not care about your structural market value; they will rip out everything, max out their bill, and leave you legally trapped by the 50% rule when it comes time to rebuild.
At AMO Excellence, we manage the entire ecosystem. As a fully licensed General Contracting firm specializing in Southwest Florida’s unique coastal challenges, we protect you from day one.
- Strategic Mitigation: We only demolish what is medically and structurally necessary, ensuring we don’t unnecessarily inflate your repair costs.
- Appraisal Coordination: We help coordinate independent, licensed appraisals to maximize your home’s established baseline value before submitting your permit application.
- Xactimate Precision: We write all estimates using Xactimate software. This provides the exact, line-itemed pricing data the City of Cape Coral requires for their Substantial Damage reviews, avoiding delays or compliance rejections.
- Seamless Rebuilding: Whether we successfully keep your project under the 50% threshold for a standard custom kitchen remodel, or we need to transition into pulling permits for a fully compliant, elevated rebuild, AMO Excellence handles the architecture, permitting, and construction under one roof.
Don’t let a regulatory technicality cost you your home. If you are facing severe damage or planning a major renovation in a Cape Coral flood zone, you need a contractor who understands the law as well as they understand construction.
Contact AMO Excellence today for a professional site evaluation and let us build a compliant, strategic roadmap for your property’s recovery.